

Settlemate
Settlemate
- 4.3
- 2.24K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
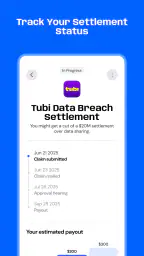
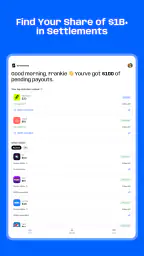
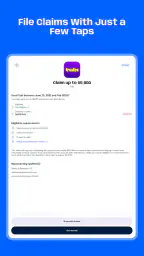
Settlemate Pros and Cons
Pros
- Simple interface makes tracking shared expenses quick and easy.
- Helps groups split bills fairly without complicated calculations.
- Useful for trips, roommates, dinners, and recurring shared costs.
- Keeps payment records organized in one central place.
- Reduces awkward conversations by clearly showing who owes what.
Cons
- Requires everyone to enter expenses accurately for reliable balances.
- May be less useful for groups that rarely share costs.
- Users may need reminders to settle outstanding payments.
- Limited usefulness if friends prefer handling payments entirely in cash.
- Privacy-conscious users may hesitate to store financial information in the app.
 Analysis by All-app
Settlemate is a finance app built around a simple but important idea: helping people notice when a company may owe them money. I found that focus more interesting than the usual budgeting approach because it looks at missed compensation, settlement opportunities, and similar situations rather than asking me to track every coffee or subscription. The developer is Settlemate, and the app is free to install, with optional purchases ranging from $2.99 to $64.99 per item.
My first impression was that this is best understood as a discovery and organization tool, not a replacement for a bank, accountant, lawyer, or government service. That distinction matters. An app can help me find a possible claim or understand an opportunity, but I still need to read the terms, decide whether the situation applies to me, and be comfortable with any information I choose to provide. The useful question is not simply “can this find money?” but “do I understand what happens after I find it?”
What Settlemate is really useful for
In everyday life, companies collect information, charge fees, change policies, and sometimes face complaints or legal action. Most people do not have the time to monitor all of that. Settlemate gives that problem a finance-app shape: instead of waiting for a notice to arrive or searching the web whenever a headline appears, I can use one place to look for opportunities that might be relevant to me.
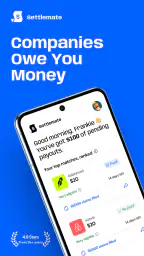
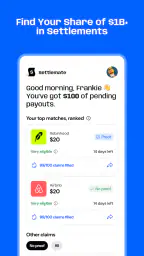
That makes it particularly appealing to people who have used many consumer services over the years and have lost track of which companies they dealt with. It may also suit someone who is comfortable checking details independently but wants a more convenient starting point. The app’s store summary, “Companies owe you money,” is brief, but it communicates the central purpose clearly without pretending to be a full financial plan.
I would not install it expecting automatic income, instant refunds, or guaranteed eligibility. A possible settlement is not the same as an approved payment, and an advertised opportunity may involve deadlines, documentation, exclusions, or a payment that is smaller than expected. The app can make the search easier; it cannot remove the need for judgment.
A realistic use case at home
Imagine I remember using several delivery, retail, travel, and digital services but cannot recall every account or purchase. I open Settlemate during a quiet moment, review the opportunities presented, and recognize one company I used regularly. Rather than submitting immediately, I compare the description with my own history, check whether the relevant dates and products match, and look for the official claim instructions. If the app helps me notice an opportunity I would otherwise miss, it has already earned its place as a practical reminder.
The important workflow is the second pass. The first pass is discovery; the second is verification. I would keep receipts, emails, account records, or order histories nearby, because memory alone is a weak basis for a financial claim. This is one of the less obvious strengths of a focused app like this: it can prompt me to search through old records with a specific purpose instead of browsing aimlessly.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Where it differs from ordinary finance apps
Traditional budgeting apps focus on spending, balances, categories, and recurring bills. They are useful when I want to control cash flow or understand where my money goes. Settlemate addresses a different moment: money that may be recoverable because of a company’s conduct or a formal resolution. I would use a budgeting app alongside it, not instead of it.
Searching manually through news articles and general web results can reveal more background, but it is slower and easier to abandon. A browser search also produces plenty of irrelevant pages, outdated discussions, and commentary that may not explain what a person must actually do. Settlemate’s value is convenience and focus. The trade-off is that I should treat it as a starting point and inspect the underlying details before making a decision.
It is also different from a tax app or a personal investment service. It does not belong in the same mental category as filing taxes, buying securities, or managing a bank account. Anyone looking for those functions will need another tool. Settlemate’s narrower purpose is a benefit when I want a quick check, but a limitation when I expect an all-in-one financial dashboard.
Trust begins with what I can see
Financial apps deserve a higher level of caution than casual entertainment apps. I look for clear explanations, visible choices, understandable account controls, and a straightforward path to stop using the service. With Settlemate, I would pay close attention to each screen before continuing, especially when the app asks for personal details or presents a possible claim.
I do not assume that a polished interface proves anything about privacy or reliability. Instead, I would read the app’s permission prompts and privacy information directly, notice which choices are optional, and avoid granting access that is not necessary for the task in front of me. If I only want to browse opportunities, I would begin with the smallest amount of information possible and see whether the app remains useful without deeper account access.
This cautious approach is not meant to make the app sound suspicious. It is simply the right habit for any service connected with financial matters. The developer, Settlemate, has made a focused product, but trust should come from understandable user choices and consistent behavior rather than from the category label alone.
Account decisions I would make carefully
Before creating or expanding an account, I would ask myself what I need the account to do. If I only want occasional browsing, I would avoid treating registration as automatic. If an account is necessary for saving items or continuing a process, I would use a strong, unique password and keep track of the email address associated with it. I would also review available account settings after signing in rather than assuming I will find them later.
Another practical step is separating browsing from submitting. I would first learn what an opportunity concerns, what information it requests, and whether the deadline is relevant. Only then would I decide whether to proceed. This reduces the chance of entering personal data simply because a prompt appeared at the end of an interesting listing.
When an app offers optional purchases, I also want the choice to be obvious. Settlemate is free to install, but in-app items can cost from $2.99 to $64.99. That range makes it especially important to review the purchase screen, understand what an item provides, and confirm that the charge is genuinely useful before accepting it. I would not pay merely because an opportunity sounds urgent or because a button is visually prominent.
Moments when personal data matters most
The most sensitive point is not opening the app; it is moving from general information to a specific claim or account action. At that stage, I would slow down and check why each requested detail is needed. Names, contact details, purchase records, account identifiers, and other information can have different levels of sensitivity. I would not provide more than the process requires, and I would avoid uploading documents until I had read the explanation surrounding the request.
I would also be alert to messages that create unnecessary pressure. A legitimate financial decision should still leave me enough time to understand the terms. If a screen encourages immediate action without explaining eligibility, payment expectations, or the next step, I would pause and investigate through an official source. This is a useful safeguard whether I discovered the opportunity in Settlemate, an email, or a web search.
Notifications deserve the same thought. A reminder can be helpful when it points me back to something I intentionally saved or started. It can become irritating when it pushes me toward repeated checking or makes every possible opportunity feel urgent. I would adjust notification choices to match how often I genuinely want to review the app, rather than allowing alerts to dictate my attention.
How I would verify a possible opportunity
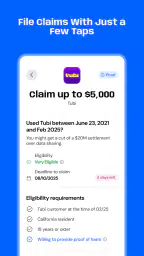
My preferred process has several stages. First, I would identify the company and the event being discussed. Second, I would compare the relevant dates, product or service, and location with my own experience. Third, I would read the eligibility language and any deadline carefully. Finally, I would use the official instructions connected with the matter and save a copy of any confirmation I receive.
This method protects against a common mistake: confusing recognition with eligibility. Seeing a familiar company name does not prove that I qualify. I might have used the service outside the relevant period, purchased an excluded product, or lack the required documentation. Settlemate can help me notice the possibility, but the final decision should be based on the actual rules.
I would keep a small record of what I submitted, when I submitted it, and which email address I used. That habit is valuable because financial follow-up can become confusing when several claims or requests are active. It also gives me something to check if a message arrives later and I am unsure whether it relates to an action I took.
Everyday strengths and practical friction
The app’s strongest quality is its narrow purpose. I do not have to turn it into a full financial-management system to get value from it. A short review session can act as a periodic check for opportunities I might not encounter through normal budgeting. Its free entry point also makes trying the basic experience less intimidating than committing to a paid financial service from the start.
The same narrow focus creates limits. If I want detailed spending analysis, bill negotiation, credit monitoring, tax preparation, or investment tracking, this is not the right tool. I would be frustrated if I expected one app to handle all of those jobs. Settlemate makes more sense as a companion to the tools I already use.
There is also a psychological trade-off. Searching for money that may be owed can feel rewarding, but not every result will lead to a payment. I would judge the app by whether it helps me make informed decisions and saves search time, not by assuming every listed possibility will produce a meaningful return. That expectation keeps the experience useful instead of turning it into a hunt for guaranteed cash.
Who should use it and who should skip it
I think Settlemate is a good fit for curious consumers who want a focused way to review possible company-related payments and are willing to verify details themselves. It may be especially useful for people who have dealt with many brands, moved between services, or rarely read consumer-rights news. It can also help organized users maintain a simple record of opportunities they have checked.
I would skip it if I am uncomfortable reviewing eligibility rules, managing account choices, or making decisions about personal information. Someone who wants a hands-off service that guarantees a result will probably be disappointed. I would also choose a different finance app if my main goal is budgeting, tracking investments, preparing taxes, or monitoring everyday spending.
For families, I would be careful about mixing records. A household may have several people who used the same company, but eligibility and documentation can differ from person to person. I would keep each person’s information separate and avoid assuming that one account or one purchase history covers everyone.
Compatibility, cost, and ongoing expectations
Settlemate is available for Android users running version 8.0 or later, and its current version is 4.5.1. That makes checking device compatibility straightforward before installation. The app is rated for Everyone, although the financial decisions inside it still deserve adult attention and careful reading.
Its public reception is encouraging without being a substitute for my own assessment: it holds a 4.3 average from around 37 thousand ratings, with more than 2 thousand written reviews and over 500 thousand installs. I read those figures as signs that the app has reached a meaningful audience, not as proof that every user will have the same experience. Reviews can reveal recurring friction, but they cannot tell me whether a particular opportunity applies to my circumstances.
The free installation lowers the barrier to testing the basic workflow. The optional purchase range means I would keep an eye on checkout screens and device-level purchase controls, particularly if other people share the device. I would want to know what I am buying before confirming, and I would keep receipts for any transaction.
My cautious verdict after using it
Settlemate is most convincing when I treat it as a focused financial-awareness tool. It can help bring overlooked possibilities into view, give me a reason to search old records, and make a scattered topic easier to revisit. I appreciate that its central idea is practical rather than overloaded with unrelated finance features.
Still, I would not hand over personal information casually or assume that an in-app result is the final authority. My best experience with it comes from using a staged workflow: browse first, verify second, submit only when the conditions make sense, and keep a record afterward. That approach also answers the questions I would have before installing it: what is it for, when should I trust a result, how much information should I share, and when is another app better?
My recommendation is therefore measured but positive. If you want a free, specialized way to look for money-related opportunities connected with companies, Settlemate is worth trying on a compatible device. Use it as a careful starting point, not as a promise of payment or a replacement for independent verification. That mindset lets the app do what it does best while keeping the important decisions firmly in your hands.
Frequently Asked Questions
What is Settlemate and what can I use it for?
Settlemate is designed to help users organize and settle shared expenses, making it useful for roommates, couples, friends, travel groups, and event participants. You can record payments, identify who owes whom, and keep a clearer overview of group finances. Before downloading, check the current feature list because available tools may vary between Android and iOS versions.
Is Settlemate suitable for managing expenses with several people?
Yes, Settlemate can be useful when multiple people are sharing costs, such as accommodation, meals, transport, subscriptions, or household bills. The main advantage is that expenses can be kept in one place instead of being tracked through scattered messages or spreadsheets. However, every participant should enter accurate amounts and confirm payments to avoid incorrect balances.
Does Settlemate handle payments directly, or does it only calculate balances?
Settlemate primarily helps users record expenses and calculate how costs should be divided. Depending on the version and region, it may not process bank transfers or send money directly to another person. Users may still need to settle the final balance through their preferred payment service, bank application, or cash. Always review the app’s current payment-related features before relying on it.
Can I use Settlemate without creating an account or sharing sensitive information?
The information required by Settlemate can depend on its latest version, device platform, and the features you choose to use. Some expense tools allow basic tracking with limited registration, while collaboration or synchronization features may require an account. Before entering financial details, review the privacy policy, permissions, and data-handling information to understand what is collected and how it may be stored.
Is Settlemate free to download, and are there any limitations?
Settlemate may be available to download at no initial cost, but certain functions can be limited by the app’s pricing model, platform, or future updates. Possible restrictions may involve advanced organization tools, synchronization, advertisements, or premium features. Check the Google Play Store or Apple App Store listing for the current price, in-app purchases, supported devices, and subscription terms before downloading.


